
Editor’s Note: Yes, it’s time to buy physical precious metals.
After more than a decade of chained stimulus packages and extremely low rates, with trillions of dollars of monetary stimulus fueling elevated asset valuations and incentivizing an enormous leveraged bet on risk, the idea of a controlled explosion or a “soft landing” is impossible.
In an interview with Marketplace, the Federal Reserve chairman admitted that “a soft landing is really just getting back to 2 percent inflation while keeping the labor market strong. And it’s quite challenging to accomplish that right now.” He went on to say that “nonetheless, we think there are pathways … for us to get there.”
The first problem of a soft landing is the evidence of the weak economic data. While headline unemployment rate appears robust, both the labor participation and employment rate show a different picture, as they have been stagnant for almost a year. Both the labor force participation rate, at 62.2 percent, and the employment-population ratio, at 60.0 percent remain each 1.2 percentage points below their February 2020 values, as the April Jobs Report shows. Real wages are down, as inflation completely eats away the nominal wage increase. According to the Bureau of Labor Statistics, real average hourly earnings decreased 2.6 percent, seasonally adjusted, from April 2021 to April 2022. The change in real average hourly earnings combined with a decrease of 0.9 percent in the average workweek resulted in a 3.4 percent decrease in real average weekly earnings over this period.
The University of Michigan consumer confidence in early May fell to an eleven-year low of 59.1, from 65.2, deep into recessionary territory. The current conditions index fell to 63.6, from 69.4, but the expectations index plummeted to 56.3, from 62.5.
The second problem of believing in a soft landing is underestimating the chain reaction impact of even allegedly small corrections in markets. With global debt at all-time highs and margin debt in the US alone at $773 billion, expectations of a controlled explosion where markets and the indebted sectors will absorb the rate hikes without a significant damage to the economy are simply too optimistic. Margin debt remains more than $170 billion above the 2019 level, which was an all-time high at the time.
However, the biggest problem is that the Federal Reserve wants to curb inflation while at the same time the Federal government is unwilling to reduce spending. Ultimately, inflation is reduced by cutting the amount of broad money in the economy, and if government spending remains the same, the efforts to reduce inflation will only come from obliterating the private sector through higher cost of debt and a collapse in consumption. You know that the economy is in trouble when the fiscal deficit is only reduced to $360 billion in the first seven months of fiscal year 2022 despite record receipts and the tailwind of a strong recovery in GDP. Now, with GDP growth likely to be flat in the first six months but mandatory and discretional spending still virtually intact, government consumption of monetary reserves is likely to keep core inflation elevated even if oil and gas prices moderate.
The Federal Reserve cannot expect a soft landing when the economy did not even take off, it was bloated with a chain of newly printed stimulus packages that have made the debt soar and created the perverse incentive to monetize all that the Federal government overspends.
The idea of a gradual cooling down of the economy is also negated by the reality of emerging markets and European banks. The relative strength of the US dollar is already creating enormous financial holes in the assets of a financial system that has built the largest carry trade against the dollar in decades. It is almost impossible to calculate the nominal and real losses in pension funds and the negative result of financial institutions in the most aggressively priced assets, from socially responsible investment and technology to infrastructure and private equity. We can see that markets have lost more than $7 trillion in capitalization in the year so far with a very modest move from the Federal Reserve. The impact of these losses is not evident yet in financial institutions, but the write downs are likely to be significant into the second half of 2022, leading to a credit crunch exacerbated by rate hikes.
Central banks always underestimate how quickly the core capital of a financial institution can dissolve into inexistence. Even the financial system itself is unable to really understand the complexity of the cross-asset impact of a widespread slump in extremely generous valuations throughout all kinds of assets. That is why stress tests always fail. And financial institutions all over the world have abandoned the healthy process of provisioning expecting a lengthy and solid recovery.
The Federal Reserve tries to convince the world that rates will remain negative in real terms for a long time, but borrowing costs globally are surging while the US dollar is strengthening, creating an enormous vacuum effect that can create significant negative effects on the real economy before the Federal Reserve even realizes that the market is weaker than they anticipated, and liquidity is significantly lower than they calculated.
There is no easy solution. There is no possible painless normalization path. After a massive monetary binge there is no soft hangover. The only thing that the Federal Reserve should have learnt is that the enormous stimulus plans of 2020 created the worst outcome: stubbornly high core inflation with weakening economic growth. There are only two possibilities: To truly tackle inflation and risk a financial crisis led by the US dollar vacuum effect or to forget about inflation, make citizens poorer and maintain the so-called bubble of everything. None is good but they wanted a decisive and unprecedented response to the pandemic lockdowns and created a decisive and unprecedented global financial risk. They thought money creation was not an issue and now the accumulated risk is so high it is hard to see how to tackle it.
One day someone may finally understand that supply shocks are addressed with supply-side policies, not with demand ones. Now it is too late. Powell will have to choose between the risk of a global financial meltdown or prolonged inflation.
About the Author
Daniel Lacalle, PhD, economist and fund manager, is the author of the bestselling books Freedom or Equality (2020), Escape from the Central Bank Trap (2017), The Energy World Is Flat (2015), and Life in the Financial Markets (2014).
He is a professor of global economy at IE Business School in Madrid.
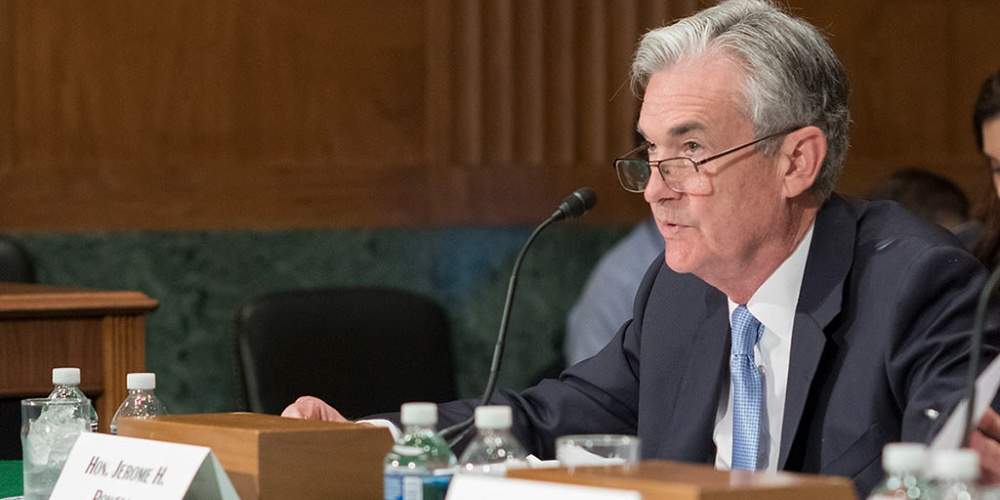
Image by Federalreserve via Flickr, Public Domain. Article cross-posted from Mises.
Two Storms, One Harvest

Every food crisis in living memory has been a one-shock event. The 2008 price spike was a commodity bubble. The 2020 shortages were a logistics failure. The 2022 grain scare was a war on one exporter’s ports. Each time, the system bent, adjusted, and recovered, and each time the experts assured us afterward that global markets are simply too big and too diversified to fail.
What nobody in Washington seems eager to discuss is that 2026 is shaping up to be something the modern food system has never actually faced. Two independent shocks, one climatic and one geopolitical, are converging on the same harvest cycle at the same time. Not sequentially. Simultaneously.
Start with the weather. The Pacific Ocean is currently building toward what forecasters now openly call a record event. NOAA’s Climate Prediction Center puts the odds of at least a strong El Niño near 88 percent, with roughly two in three odds it reaches “very strong” status, the tier reserved for perhaps three or four events in the entire satellite era. Every major global model now projects a median peak in Super El Niño territory, and most of them project it exceeding the 2015-16 event, which until now held the modern record. Sea surface anomalies were already brushing the super threshold in mid-July, months before these events normally peak. The atmosphere has already shifted into El Niño mode, and the event is forecast to crest in late fall and early winter.
This is not about “climate change.” It’s about the standard cycles of weather, and the cycle we’re currently in is one that has likely devastated societies in the past. We’re better prepared as a society today, but not all Americans are equally prepared.
Serious households have started doing the quiet math on their own. Grocery bills tell part of the story, and the forecast maps tell the rest, which is why long-term food storage has moved from fringe hobby to mainstream line item in the family budget, with established suppliers like Heaven’s Harvest seeing demand from people who five years ago would have rolled their eyes at the idea. That instinct is not paranoia. It is pattern recognition, and the pattern is worth walking through carefully.
Editor’s Note: Heaven’s Harvest IS a sponsor, but the warnings of this article are real and would be written even if we didn’t have a survival food sponsor. With that said, those who take advantage of what they offer can use promo code “Patriot” for 15% off.
The Fertilizer Clock Is Already Running
While the Pacific warms, the second shock has been unfolding in the Strait of Hormuz. The conflict with Iran turned the world’s most important energy chokepoint into a contested waterway, and the consequences reach far beyond the gas pump. Roughly a third of global fertilizer trade moves through Hormuz, and the disruption sent urea prices up 86 percent year over year by March, with a 53 percent jump in a single month.
The World Bank projects energy prices rising about 24 percent in 2026 and fertilizer about 31 percent. By its own accounting, fertilizer prices ran 35 percent higher in the first five months of this year than the same period last year.
Here is the mechanism the nightly news will not explain. Fertilizer is not a grocery item. It is a time-delayed input. The nitrogen a farmer in Iowa or Punjab could not afford to apply this spring does not show up as a problem this spring. It shows up as a thinner harvest six to twelve months later.
The World Bank’s own food security brief concedes that the effects of reduced applications earlier this season “are likely to become visible only later in harvest outcomes.” Translate that from institutional language into plain English and it means this. The damage is already done, it is already in the ground, and we are simply waiting for it to arrive on the shelf.
Now check the calendar. Six to twelve months from the spring planting season lands us squarely in late 2026 and early 2027. Which is precisely when the strongest El Niño in the instrumental record is forecast to peak, bringing its signature droughts to Southeast Asia, Australia, southern Africa, northern Brazil, and South Asia, the very regions that grow the world’s rice, sugar, and oilseeds.
The World Bank warns openly that a strong El Niño “could disrupt multiple crop belts simultaneously” on top of the conflict-driven input costs. Their baseline projection assumes the Middle East disruptions ease by autumn. What in the last two years of Middle East history suggests that assumption is safe?
The System Has No Slack Left
The comfortable answer is that global markets always adjust. But adjustment requires slack, and the slack is gone. Global cereal production is expected to decline from last year’s records even before El Niño does its work. The UN World Food Programme, hardly a den of right-wing preppers, is calling this the most significant disruption to its supply chains since Covid and the invasion of Ukraine, and its supply chain director put the stakes bluntly.
Today’s supply chain challenges are tomorrow’s hunger crisis.
There is also a political dimension that markets cannot price. When food gets scarce, governments do not behave like economists. They behave like politicians. Export bans, hoarding mandates, and panic buying at the national level turned the modest rice shortfall of 2008 into a global crisis, and analysts are already warning that import-dependent nations are the first dominoes.
The 2015-16 Super El Niño, a far weaker event than what is now forecast, threw tens of millions into food stress across Africa and Asia. This one is projected to be stronger, and it arrives with fertilizer already rationed by price and shipping lanes already contested by missiles.
What Joseph Knew
Scripture does not treat preparation for lean years as faithlessness. It treats it as wisdom delivered in advance to those willing to act on it.
Behold, there come seven years of great plenty throughout all the land of Egypt: And there shall arise after them seven years of famine; and all the plenty shall be forgotten in the land of Egypt.
Joseph did not respond to that warning with a hashtag or a committee. He stored grain during the years of abundance, and when the famine came, Egypt stood while its neighbors begged. The lesson is not that famine is certain. It is that the time to prepare is precisely when preparation still looks optional.
Nobody who filled a pantry in a year of plenty has ever regretted it, and nobody standing in an empty aisle has ever been glad he waited for certainty.
None of this calls for panic, and panic is the enemy of sound judgment anyway. It calls for the same unglamorous prudence our grandparents considered ordinary. Keep some cash margin, know your local growers, and put real food in deep storage while it is cheap and available, because the entire arc of this story is that cheap and available is a closing window.
Families looking for a straightforward place to start can visit Heaven’s Harvest and use promo code Patriot for 15 percent off long-term storable food. The forecasts may yet soften, the strait may yet reopen, and we should pray they do. But hope is a fine thing to hold and a foolish thing to eat.
